Key Takeaways & Executive Summary
- Eldest Member Premium Rule: In a family floater health insurance policy, the annual premium is determined exclusively by the age of the oldest insured individual. Adding senior citizen parents (age 60+) to a young family floater instantly doubles or triples the aggregate premium.
- The “Split-Floater” Institutional Strategy: The most cost-effective and risk-optimized health portfolio architecture separates the nuclear family (Self, Spouse, Children) into one Family Floater, while placing Parents onto separate Individual Mediclaim or dedicated Senior Citizen plans.
- Restoration Benefit Safeguards: Modern family floaters feature automatic restoration (recharge) triggers that replenish 100% of the sum insured upon exhaustion. However, policyholders must audit whether restoration applies to the same illness or only unrelated hospitalizations.
- No Claim Bonus (NCB) Preservation: In a family floater, a single hospitalization claim made by any member reduces or eliminates the accumulated No Claim Bonus for the entire family. Individual plans protect NCB independently for each healthy family member.
- Tax Optimization Under Section 80D: Structuring separate policies for nuclear family and parents enables maximum tax deductions under the Old Tax Regime: ₹25,000 for self/spouse/kids plus an additional ₹50,000 for senior citizen parents (total ₹75,000 annual tax relief).
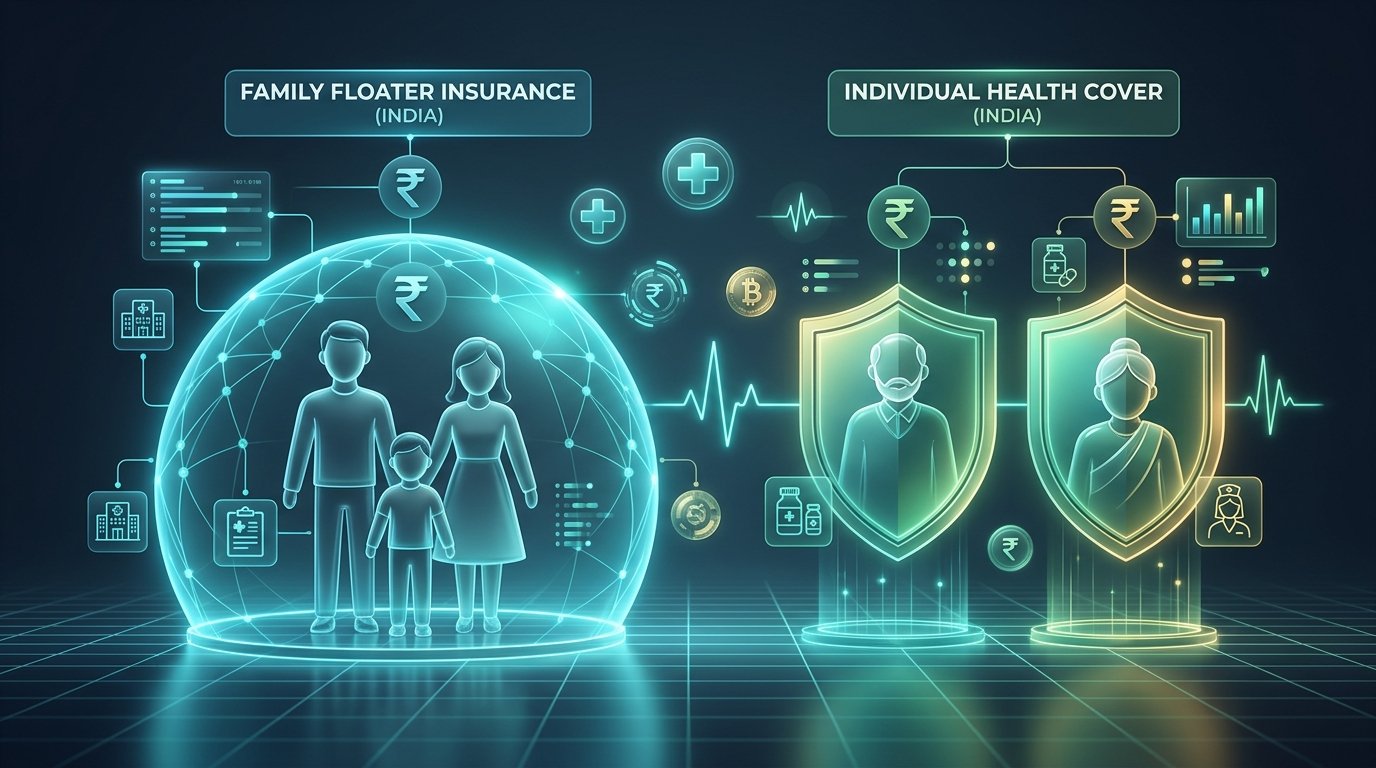
Family Floater vs Individual Health Insurance: Individual health insurance assigns a dedicated, independent sum insured to each family member (e.g., ₹10 Lakhs each for 4 members = ₹40 Lakhs total coverage), whereas a Family Floater pools a single combined sum insured (e.g., ₹10 Lakhs shared) accessible by any or all covered members during the policy year. While family floaters offer significant premium economy for young, healthy families, individual plans provide isolated risk firewalls for senior citizens and individuals with chronic ailments.
Understanding the Core Architectural Dilemma
Constructing a robust healthcare risk firewall is the foundational prerequisite before deploying capital into equity mutual funds, SIPs, or wealth-building vehicles. Without adequate health insurance, a single multi-week hospitalization involving cardiovascular surgery, oncology protocols, or intensive critical care can obliterate five to ten years of disciplined compounding in a matter of days.
However, when retail investors in India set out to purchase private health cover, they encounter a critical structural crossroad: Should you purchase a single Family Floater policy covering everyone, or should every family member hold an Individual Mediclaim contract? Making the wrong choice leads to either exorbitant, budget-breaking annual premiums or catastrophic underinsurance during concurrent hospital emergencies.
Deep Dive: What is Individual Health Insurance?
An Individual Health Insurance policy is a standalone, dedicated contract where the sum insured belongs exclusively to one specified individual. If a household purchases individual policies of ₹15 Lakhs each for Husband (35), Wife (32), and Child (6), the family maintains an aggregate medical security cushion of ₹45 Lakhs across three isolated compartments.
Primary Advantages of Individual Health Insurance:
- Isolated Risk & Complete Claim Independence: If the husband undergoes an emergency surgical intervention costing ₹12 Lakhs, his available cover for that policy year reduces to ₹3 Lakhs (prior to restoration). However, the wife and child still hold their untouched, 100% pristine ₹15 Lakhs coverage intact.
- Individual No Claim Bonus (NCB) Accumulation: Under IRDAI guidelines, insurers reward claim-free years by augmenting the sum insured by 10% to 50% annually (up to a 100% or 200% maximum cap) without charging extra premium. In individual policies, if the husband files a claim, only his personal policy forfeits the bonus; the wife and child continue compounding their independent NCB buffers.
- Customized Coverage & Specific Riders: Each family member can tailor their policy terms. For instance, the wife’s policy can incorporate comprehensive maternity and newborn riders, while the husband’s policy incorporates high-risk accidental disability riders.
- Essential for Chronic Disease Management: If one family member suffers from a Pre-Existing Disease (PED) such as Type-2 diabetes, hypertension, or asthma, underwriter loadings (extra premium) and extended waiting periods apply exclusively to that individual’s policy, leaving the rest of the family’s contracts unencumbered at standard standard rates.
Deep Dive: What is Family Floater Health Insurance?
A Family Floater health insurance policy wraps the entire family unit under a single umbrella contract with one unified sum insured. If the family purchases a ₹20 Lakh Family Floater, that single ₹20 Lakh corpus floats among all covered individuals. If the husband requires ₹5 Lakhs for dengue hospitalization, ₹15 Lakhs remains available for any other family member for the rest of the policy year.
Primary Advantages of Family Floater Insurance:
- Substantial Premium Economy for Young Families: For a young nuclear family (e.g., husband age 30, wife age 28, child age 2), the probability of multiple members requiring simultaneous major hospitalization in the same 12-month calendar window is statistically minuscule (under 0.5%). A ₹15 Lakh family floater costs approximately 30% to 45% less than purchasing three separate ₹15 Lakh individual policies.
- Administrative Simplicity: One policy schedule, one renewal premium reminder date, one customer portal login, and one health card portfolio. Families avoid managing multiple premium due dates across different months.
- Flexible Cushion for Children: Young children rarely require high-cost major surgeries; their health events are typically brief hospitalizations for seasonal viral infections, pneumonia, or minor sports fractures. A family floater allows children to tap into a high corporate-grade sum insured (e.g., ₹25 Lakhs) without parents paying for an expensive individual adult policy for a toddler.
Structural Comparison: Family Floater vs Individual Health Plans
| Key Feature | Individual Health Insurance | Family Floater Health Insurance |
|---|---|---|
| Sum Insured Allocation | Dedicated independently to each person. Non-transferable between members. | Unified shared pool. Accessible by any single member or multiple members. |
| Premium Determinant | Calculated individually based on each member’s exact entry age and health profile. | Driven entirely by the chronological age and medical risk of the oldest member. |
| Impact of a Claim on Others | Zero impact. Other family members retain full untouched sum insured and NCB. | Reduces the remaining shared pool for the rest of the year. NCB resets for all. |
| Ideal Candidate Profile | Senior citizens (60+), individuals with diabetes/cardiac history, large age gaps. | Young nuclear families (Self, Spouse, 1-2 minor kids) with similar age bands. |
| Cost Efficiency | Higher aggregate premium when insuring multiple young individuals. | High cost efficiency; 25% to 40% cheaper for young households. |
| Child Exit Age Rule | Lifelong renewal with no age restrictions. | Children must exit floater at age 25 (converted to individual plan with portability). |
The Fatal Pitfall: “The Eldest Member Trap” Explained
The single most catastrophic financial mistake Indian families commit when purchasing health insurance is clubbing elderly parents (Father aged 64, Mother aged 60) into the same family floater policy along with the earning son (aged 32), daughter-in-law (aged 29), and grandchild (aged 3).
To understand why this is disastrous, let us examine the mathematics of health underwriting:
The Mathematical Trap of Clubbing Parents with Children
In a Family Floater, the underwriting actuarial engine prices the entire group using the mortality and morbidity table of the oldest insured individual. If a 64-year-old father is listed, the insurer charges the high-risk senior citizen premium rate for all members. Furthermore, elderly individuals have an annual hospitalization probability exceeding 18-25%. If the father files two claims totaling ₹8 Lakhs from a ₹10 Lakh floater, the entire young nuclear family is left with a precarious ₹2 Lakh buffer for the remainder of the year!
Numerical Case Study: Clubbed Floater vs The Split-Floater Strategy
Consider a 5-member family: Husband (35), Wife (32), Daughter (4), Father (64), and Mother (60) seeking ₹15 Lakhs of health protection. Let us evaluate the cost and risk outcomes under two distinct architectures:
| Strategy Architecture | Policy Structure | Est. Annual Premium | Available Security Cushion |
|---|---|---|---|
| Approach A: Unified 5-Member Floater (Flawed) | Single ₹15 Lakh Floater covering all 5 members (priced at 64-yr father rate). | ₹58,000 – ₹68,000 / year | Only ₹15 Lakhs shared among 5 people. Frequent senior claims deplete cover for the young child. |
| Approach B: The “Split-Floater” Institutional Model (Recommended) |
Policy 1: Nuclear Family Floater (Self + Wife + Child) for ₹15 Lakhs. Policy 2: Senior Parents Floater / Individual (Father + Mother) for ₹15 Lakhs. |
Policy 1: ₹16,500 Policy 2: ₹42,000 Total: ₹58,500 / year |
₹30 Lakhs total coverage! Isolated firewalls. Nuclear family retains 100% NCB and ₹15L uninterrupted cover regardless of parents’ claims. |
The Insight: For virtually the identical annual premium (₹58,500 vs ₹62,000), the Split-Floater Strategy delivers double the total medical protection (₹30 Lakhs vs ₹15 Lakhs), preserves the nuclear family’s pristine NCB compounding, and eliminates the risk of an elderly hospitalization draining coverage needed for the young child.
Restoration & Recharge Benefits: Fine Print You Must Audit
To market family floaters aggressively, insurance distributors emphasize “100% Automatic Restoration” or “Unlimited Refill Benefits.” While restoration is a vital safety net, policyholders must understand the three distinct technical variants permitted under IRDAI regulations:
- Complete Exhaustion vs Partial Trigger: In older policy wordings, the restoration engine only activates when the basic sum insured AND accumulated NCB are reduced to exactly zero (0). In modern consumer-friendly contracts, partial exhaustion triggers instant proportionate restoration.
- Related vs Unrelated Illness Restriction: Many budget floaters enforce a severe restriction: restoration cannot be utilized for the same illness in the same policy year. For example, if the husband exhausts ₹10 Lakhs treating cardiovascular complications, the restored ₹10 Lakhs cannot be used if he suffers a cardiac recurrence within that same policy year; it can only be used for an unrelated disease (e.g., cancer or accident). Premium comprehensive policies now offer “Unlimited Any Illness” restoration.
- Single Claim Cap: Restoration cannot be utilized in a single hospitalization invoice. If your hospital bill is ₹18 Lakhs on a ₹10 Lakh policy with 100% restoration, the policy will pay ₹10 Lakhs and require you to fund the remaining ₹8 Lakhs out of pocket; the restored ₹10 Lakhs becomes available only for subsequent distinct admissions.
Section 80D Income Tax Optimization: Old vs New Regime
Structuring your health insurance portfolio correctly yields substantial tax deductions under Section 80D of the Income Tax Act, 1961, when filing under the Old Tax Regime:
Section 80D Maximum Deduction Ceiling Architecture
- Nuclear Family (Self, Spouse, Dependent Children): Up to ₹25,000 per financial year (including up to ₹5,000 for preventive health check-ups).
- Senior Citizen Parents (Age 60 and Above): Up to ₹50,000 per financial year. (If parents are non-seniors, limit is ₹25,000).
- Maximum Combined Household Deduction: ₹75,000 per financial year (₹25,000 + ₹50,000). If the primary policyholder is also a senior citizen (age 60+), the total deduction ceiling expands to ₹1,00,000.
- Payment Mode Warning: Under Section 80D(2), premium payments made in cash are strictly disqualified from tax deductions. Payments must be processed electronically (UPI, NetBanking, Credit Card, Cheque). Only preventive health check-up expenses (up to ₹5,000) are permitted in cash.
The 5-Step Actionable Decision Framework: Which Plan Should You Buy?
To eliminate ambiguity, follow this institutional framework formulated by the advisory team at JGFundMart:
- Scenario 1: You are Single or Married with No Children (Ages 22 – 35): Purchase an individual policy or a 2-member Family Floater of ₹15L – ₹25L. Premiums are nominal, and you can lock in waiting periods early while in prime health.
- Scenario 2: Young Family (Self + Spouse + 1 or 2 Minor Children): Choose a Family Floater of ₹20L to ₹25L, paired with a high-deductible ₹50L or ₹1 Crore Super Top-Up policy. This delivers institutional protection at minimal premium.
- Scenario 3: Parents (Age 55+): Never add them to your nuclear floater. Buy a dedicated Senior Citizen Health Policy or separate individual plans for Father and Mother. Ensure the policy has minimal room rent sub-limits and manageable co-payment clauses.
- Scenario 4: One Family Member has a Chronic Pre-Existing Disease (e.g., Kidney Disease, Diabetes): Remove that member from the family floater and issue them an independent Individual policy with appropriate underwriting loading. Keep the healthy members on an unencumbered floater.
- Scenario 5: Children Crossing Age 25: Under IRDAI portability rules, transfer the 25-year-old child onto their own Individual Mediclaim plan prior to expiration to port all accumulated waiting period credits without break.
Financial Calculators To Calibrate Your Health & Wealth Reserves
Model your family’s health contingency cushions and long-term investment surpluses with JGFundMart’s precision tools:
Frequently Asked Questions (FAQs) – Family Floater vs Individual Plans
1. Can I convert a Family Floater to an Individual policy later without losing waiting period benefits?
Yes. Under the IRDAI Health Insurance Portability Regulations, any dependent member covered under a family floater (such as a child turning 25 or a spouse following divorce/separation) has the statutory right to migrate to an individual policy with the same insurer. All accumulated waiting period credits for pre-existing diseases and specific ailments are preserved 100% up to the previous floater sum insured.
2. What happens if two family members are hospitalized at the same time in a family floater?
Both members share the single available sum insured. If the policy has a ₹15 Lakh cover and Member A’s bill is ₹10 Lakhs while Member B’s bill is ₹8 Lakhs (total ₹18 Lakhs), the insurer will pay ₹15 Lakhs and the policyholder must pay ₹3 Lakhs out-of-pocket, unless the policy features a specific restoration clause that triggers during concurrent admissions.
3. Can I include my in-laws in my family floater policy?
Most retail health insurance policies in India restrict family floaters to the primary insured, legally wedded spouse, dependent children, and biological parents. In-laws are generally excluded from personal floaters. Even where permitted by select corporate group policies, clubbing in-laws into your primary family floater is financially detrimental due to the eldest member premium pricing rule.
4. How does No Claim Bonus (NCB) work in a family floater?
In a family floater, the No Claim Bonus is unified. If the policy accumulates a 50% bonus over 5 years (turning a ₹10 Lakh policy into ₹15 Lakhs), a claim of even ₹20,000 by any one member causes the bonus to reduce or reset according to the insurer’s rules. In individual plans, only the claimant’s bonus is impacted.
5. What is the maximum age until which dependent children can stay on a family floater?
Under standard Indian insurance guidelines, dependent children can typically remain on a family floater until age 25, provided they are unmarried and financially dependent. Upon reaching age 25 (or upon getting married/financially independent), they must be ported to their own individual policy.
6. Can I buy a Super Top-Up policy over a Family Floater?
Yes, this is one of the most effective strategies in personal finance. You can purchase a ₹15 Lakh Family Floater base policy and supercharge it with a ₹1 Crore Family Floater Super Top-Up policy featuring a ₹15 Lakh deductible. This gives your entire family institutional-grade ₹1.15 Crore protection at a fraction of the cost of a full ₹1 Crore base policy.
7. Is health insurance cashless claim settlement guaranteed at all network hospitals?
Cashless settlement is subject to pre-authorization approval by the insurer or TPA and hospital empanelment under the “Cashless Everywhere” system initiated by the General Insurance Council. In non-network or disputed billing cases, policyholders can settle invoices directly and file for reimbursement post-discharge within 30 days.