Key Takeaways & Executive Summary
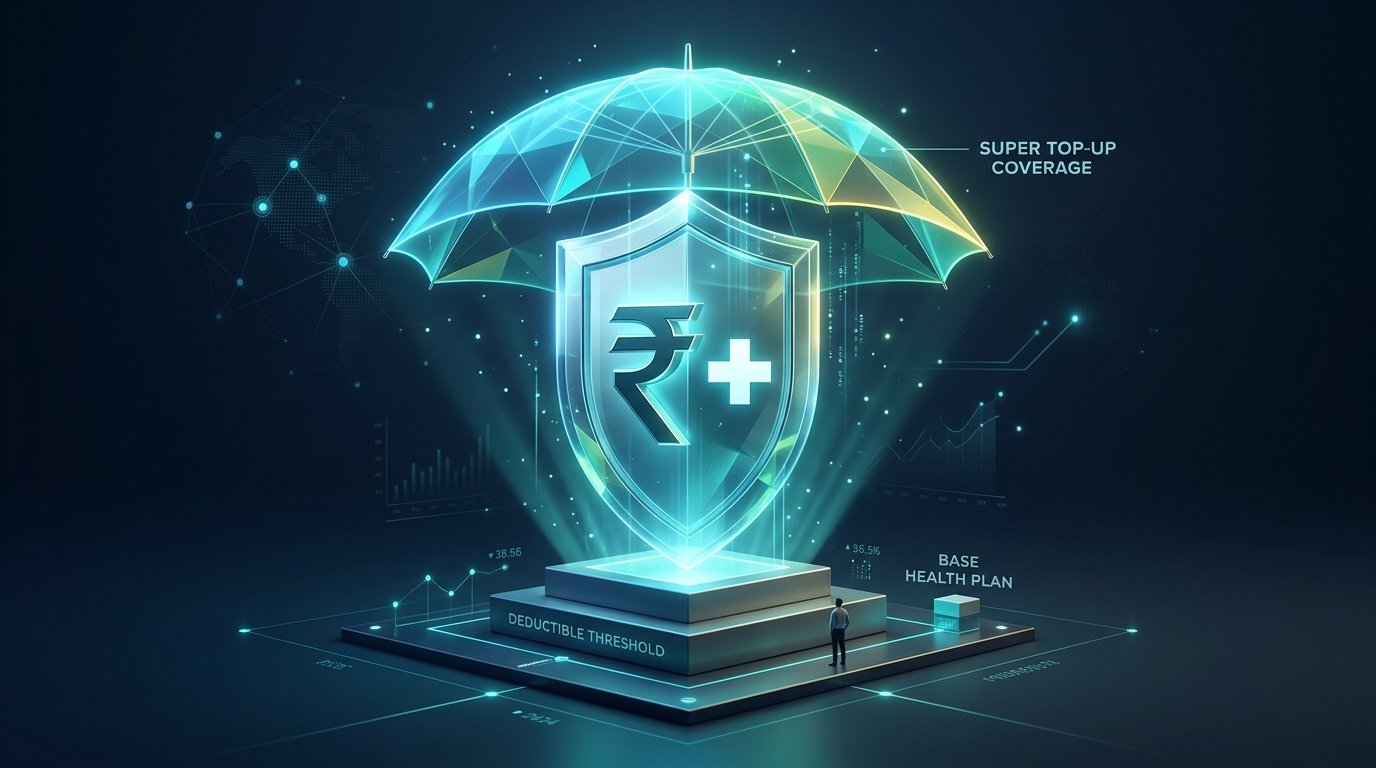
- Super Top-Up vs Regular Top-Up: Regular Top-Up policies only trigger when a single hospital admission exceeds the deductible threshold. Super Top-Up policies calculate the deductible on an aggregate cumulative basis across all hospitalizations during the entire policy year, offering exponentially superior real-world protection.
- The 60% Premium Discount Strategy: Purchasing a standalone ₹1 Crore base Mediclaim policy costs ₹45,000 to ₹70,000 annually. In contrast, combining a ₹15 Lakh base floater with an ₹85 Lakh Super Top-Up (with a ₹15 Lakh deductible) delivers the identical ₹1 Crore shield for merely ₹18,000 to ₹26,000—saving over 60% in recurring premiums.
- Corporate Shield Pairing: Salaried professionals holding an employer group health cover (e.g., ₹5 Lakhs) can purchase a personal ₹95 Lakh Super Top-Up policy with a ₹5 Lakh deductible. Your employer policy absorbs the deductible, while your personal super top-up cushions high-cost catastrophic events.
- No Insurer Alignment Required: You do NOT need to buy your base policy and Super Top-Up from the same insurance company. You can hold a base policy with Insurer A (e.g., HDFC ERGO) and a Super Top-Up with Insurer B (e.g., Care Health or Star Health).
- Tax Advantage Under Section 80D: Super Top-Up premiums qualify 100% for tax deductions alongside base health insurance under Section 80D of the Income Tax Act within the Old Tax Regime.
What is Super Top-Up Health Insurance? A Super Top-Up health insurance policy is a high-limit cost-effective medical cover that activates once cumulative admissible hospitalization expenses across an entire policy year exceed a pre-agreed financial threshold called the “deductible.” Unlike regular top-up plans that assess claims per single hospital visit, super top-up aggregates multiple admissions throughout the 12 months, allowing policyholders to secure ₹50 Lakhs to ₹1 Crore of medical protection at a fraction of standard base policy costs.
The Escalating Medical Inflation Reality in Urban India
Healthcare inflation in India is compounding at an alarming 12% to 14% annually—more than double the headline Consumer Price Index (CPI) inflation rate. Clinical interventions that cost ₹3 Lakhs a decade ago routinely command ₹8 Lakhs to ₹15 Lakhs today in Tier-1 metropolitan hospital chains.
Consider the contemporary costs of advanced tertiary and quaternary medical interventions:
- Complex Cardiovascular Interventions: Coronary artery bypass grafting (CABG) with post-operative ICU care and multiple drug-eluting stents easily costs ₹6 Lakhs to ₹12 Lakhs.
- Advanced Oncological Treatments: Modern chemotherapy regimens, robotic oncological surgeries, targeted immunotherapy, and proton beam radiation protocols span between ₹20 Lakhs and ₹45 Lakhs over a 12-to-18-month therapeutic cycle.
- Organ Transplants & ICU Prolongation: Liver, lung, or kidney transplants combined with immunosuppressive stabilization and ICU ventilation frequently breach ₹25 Lakhs to ₹50 Lakhs.
In this clinical landscape, holding a traditional ₹5 Lakh or ₹10 Lakh corporate or retail health insurance policy creates a perilous illusion of security. However, upgrading a base Mediclaim policy to ₹1 Crore through standard insurance channels presents an onerous premium barrier for middle-class families. This is precisely where the Super Top-Up Architecture emerges as an institutional game-changer.
The Critical Engineering Difference: Top-Up vs Super Top-Up
The most common and expensive misunderstanding among retail policyholders is confusing a Standard Top-Up policy with a Super Top-Up policy. Both products utilize a “deductible” mechanism, but their mathematical claim-trigger formulas are fundamentally different.
What is a “Deductible”?
A deductible is the initial threshold of medical expenses that the policyholder must bear before the top-up insurer pays a single rupee. This deductible can be settled either out-of-pocket from personal savings OR claimed through another primary insurance policy (such as a base Mediclaim or corporate group plan).
1. Standard Top-Up (Per-Claim Deductible – The Hidden Trap)
A standard top-up applies the deductible to each hospitalization event in isolation. If your policy has a ₹5 Lakh deductible and you are hospitalized three times in a year with bills of ₹4 Lakhs, ₹4 Lakhs, and ₹4 Lakhs (total medical expenses ₹12 Lakhs), the standard top-up pays ₹0 (Zero) because no individual bill exceeded the ₹5 Lakh hurdle!
2. Super Top-Up (Aggregate Annual Deductible – The Golden Standard)
A super top-up tallies your medical invoices on a cumulative, aggregate annual basis across the entire 365-day policy term. In the exact same scenario above (three admissions of ₹4 Lakhs each = ₹12 Lakhs total):
- Admission 1 (₹4 Lakhs): Covered by your base policy or paid out-of-pocket. Remaining deductible is ₹1 Lakh.
- Admission 2 (₹4 Lakhs): First ₹1 Lakh exhausts your deductible. The Super Top-Up immediately triggers and pays the remaining ₹3 Lakhs!
- Admission 3 (₹4 Lakhs): Deductible is already fully satisfied for the year; the Super Top-Up pays the entire ₹4 Lakhs!
- Total Super Top-Up Payout: ₹7 Lakhs!
Head-to-Head Comparison: Top-Up vs Super Top-Up Plans
| Key Dimension | Standard Top-Up Policy | Super Top-Up Policy (Recommended) |
|---|---|---|
| Deductible Application | Evaluated strictly on a single-claim basis per admission. | Evaluated on an aggregate cumulative basis across 365 days. |
| Multiple Hospitalizations Protection | Weak: Ineffective if multiple claims each fall below deductible. | Extremely Strong: Once deductible is breached, all further claims are covered. |
| Cost / Premium Difference | Slightly cheaper (approx. 15% to 20% lower premium than super top-up). | Marginally higher than top-up, but 60% cheaper than base policies. |
| Real-World Utility | Poor utility; leads to severe consumer disputes during claim settlement. | Superior institutional safety net for modern multi-stage illnesses. |
The ₹1 Crore Blueprint: How to Save 60% in Annual Premiums
To demonstrate the mathematical supremacy of the Super Top-Up framework, let us analyze the insurance cost structure for a 36-year-old individual with a spouse (33) and one child (5) seeking ₹1 Crore of family health protection in a Tier-1 Indian metro:
| Portfolio Structure | Architecture Breakdown | Est. Annual Premium | Total 20-Year Premium Outflow |
|---|---|---|---|
| Option 1: Pure Standalone ₹1 Crore Base Plan | Single ₹1 Crore Base Mediclaim policy with zero deductible. | ₹48,000 – ₹65,000 / year | Approx. ₹16 – ₹22 Lakhs (with age escalations) |
| Option 2: Base Floater + Super Top-Up Combo |
Base Policy: ₹15 Lakhs Floater (Zero Deductible) Super Top-Up: ₹85 Lakhs (₹15 Lakh Deductible) |
Base: ₹16,500 Super Top-Up: ₹6,500 Total: ₹23,000 / year |
Approx. ₹7.5 – ₹9 Lakhs (Saves ₹8.5 to ₹13 Lakhs in pure cash!) |
The Compounding Dividend: By adopting Option 2, the family saves approximately ₹25,000 to ₹35,000 every single year in premiums while holding the identical ₹1 Crore medical safety cushion. If that saved ₹30,000 annual differential is redirected into a disciplined Equity Index or Flexi-Cap Mutual Fund SIP compounding at an assumed 12.5% CAGR over 20 years, it accumulates into an extraordinary wealth cushion of ₹28.4 Lakhs!
How to Settle a Claim Using Base and Super Top-Up Together
A frequent apprehension among investors is whether navigating two different insurance policies during a hospital emergency becomes an administrative nightmare. When properly executed under IRDAI Master Guidelines, the claim protocol is straightforward:
Scenario: A ₹25 Lakh Hospital Bill with a ₹10L Base Plan and ₹90L Super Top-Up (₹10L Deductible)
- Step 1: Cashless Pre-Authorization for Base Policy: Upon hospital admission, submit your Base Mediclaim health card to the hospital’s Third-Party Administrator (TPA) desk. The base insurer issues cashless pre-authorization up to your base limit (₹10 Lakhs).
- Step 2: Intimate the Super Top-Up Insurer: Simultaneously send a formal claim intimation notice to your Super Top-Up insurer informing them that total estimated hospitalization expenses will exceed the ₹10 Lakh deductible.
- Step 3: Discharge & Settlement: Upon discharge, the base policy settles the first ₹10 Lakhs directly with the hospital.
- Step 4: Super Top-Up Claim Submission: Request the hospital TPA desk to provide the discharge summary, original consolidated hospital bill, and a certified Settlement Letter from the base insurer confirming that ₹10 Lakhs was disbursed. Submit these documents along with the super top-up claim form. The super top-up insurer disburses the remaining ₹15 Lakhs without friction.
5 Essential Clauses to Audit Before Purchasing Super Top-Up
Not all super top-up policies are created equal. When selecting a contract, ensure your policy passes this rigorous 5-point audit:
- 1. Zero Room Rent Sub-Limits: Many budget super top-up plans impose a 1% sum insured or single private room ceiling. In a ₹1 Crore policy, room rent should be “Single Private Room of Choice” or “No Room Rent Cap” to prevent proportional deduction penalties across doctor consultations and surgery fees.
- 2. Pre- and Post-Hospitalization Window: Ensure the policy provides at least 60 days pre-hospitalization and 180 days post-hospitalization coverage for diagnostic scans, follow-up tests, and prescription drugs.
- 3. Pre-Existing Disease (PED) Waiting Period Alignment: Check the waiting period for pre-existing ailments (hypertension, diabetes, thyroid). Premium policies offer 1-year or 2-year waiting periods, while standard policies mandate 36 months.
- 4. Daycare Treatment Coverage: Modern surgical advancements (cataracts, kidney stone lithotripsy, arthroscopy) do not require 24-hour hospitalization. Verify that the policy covers all daycare procedures without sub-limits.
- 5. Organ Donor Expenses: High-cost transplant surgeries require harvesting organs from living donors. Ensure the super top-up covers hospital charges incurred by the donor up to the sum insured.
IRDAI 100% Cashless Turnaround Mandate: The New Era of Super Top-Up Claims
Historically, policyholders feared that coordinating claims between two insurers would result in excruciating discharge delays. However, under the revolutionary master circular issued by the Insurance Regulatory and Development Authority of India (IRDAI), strict statutory turnaround times (TAT) are now enforceable across all general and standalone health insurers in India:
- 1-Hour Initial Cashless Authorization: Insurers and Third-Party Administrators (TPAs) are legally mandated to communicate their decision on cashless authorization requests within 60 minutes of receiving the hospital’s pre-authorization request.
- 3-Hour Final Discharge Clearance: Once the hospital transmits final medical summary invoices upon clinical discharge, the insurer must issue the final settlement approval within 3 hours. In the event of unjustified delays exceeding 3 hours, any additional hospital bed or nursing charges incurred must be borne entirely by the insurance company, not the patient.
- Cashless Everywhere Protocol: Under the nationwide initiative, policyholders can access cashless hospitalization even in non-empanelled hospitals, provided the medical center has at least 15 beds and complies with state clinical establishment regulations, giving your ₹1 Crore Super Top-Up frictionless reach across the length and breadth of India.
The Corporate Employee Strategy: Shielding Your Career Transition
If your employer provides a ₹5 Lakh corporate group health insurance cover, you have a golden opportunity to build a low-cost fortress. You can buy a personal ₹95 Lakh Super Top-Up policy with a ₹5 Lakh deductible for as low as ₹3,500 to ₹5,500 per year!
As long as you are employed, your employer’s policy seamlessly absorbs the ₹5 Lakh deductible, while your super top-up protects you against major medical catastrophes. If you switch jobs or retire, you can easily bridge the deductible gap by procuring a personal ₹5 Lakh base Mediclaim policy without losing your accumulated super top-up continuity benefits.
Financial Calculators To Calibrate Your Capital Allocation
Model how optimizing your insurance premiums empowers you to compound wealth faster. Use our free financial tools:
Frequently Asked Questions (FAQs) – Super Top-Up Health Insurance
1. Is it mandatory to buy a base policy and Super Top-Up from the same insurer?
No, it is not mandatory. You are free to purchase your base policy from Insurer A (e.g., Star Health) and your Super Top-Up from Insurer B (e.g., HDFC ERGO or Care Health). The Super Top-Up insurer only requires certified copies of hospital bills and the base insurer’s settlement summary letter to disburse claims exceeding the deductible.
2. Can I claim cashless settlement on a Super Top-Up policy?
Yes. If both the base and super top-up policies are with the same insurer, cashless settlement is seamless. If they are with different insurers, cashless settlement is readily available if the hospital TPA desk coordinates with both insurers, or the policyholder can process the base cashless and claim the remaining super top-up amount via fast reimbursement within 30 days of discharge.
3. What happens if I don’t have a base policy at all? Can I still buy a Super Top-Up?
Yes, you can buy a Super Top-Up policy even without holding a base health insurance policy. However, you will have to pay the entire deductible amount (e.g., ₹5 Lakhs or ₹10 Lakhs) out of your own personal savings before the super top-up pays the balance. Therefore, holding an underlying base policy matching the deductible is strongly recommended.
4. How does the deductible reset in a Super Top-Up policy?
The deductible applies on an annual policy-year cycle. Every time your policy renews for a new 12-month period, the deductible resets back to zero. You must cross the deductible threshold again during that new policy year before claims are payable.
5. Does Super Top-Up premium qualify for Section 80D tax deductions?
Yes. Premiums paid towards Super Top-Up health insurance policies qualify 100% for tax deductions under Section 80D of the Income Tax Act up to the standard limits (₹25,000 for self/family, and up to ₹50,000 for senior citizen parents) under the Old Tax Regime.
6. Are pre-existing diseases covered under Super Top-Up health insurance?
Yes, pre-existing diseases are covered after completing the policy’s specified waiting period (typically 24 to 36 months from policy inception). It is crucial to disclose all pre-existing conditions accurately during proposal submission to ensure seamless claim clearance under Section 45.
7. Can I buy a Super Top-Up for my senior citizen parents?
Yes. Super Top-Up policies are an outstanding way to provide ₹25 Lakh to ₹50 Lakh coverage for senior citizen parents at affordable rates. When choosing a plan for elderly parents, ensure the policy has no stringent room-rent caps or co-payment clauses.